Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
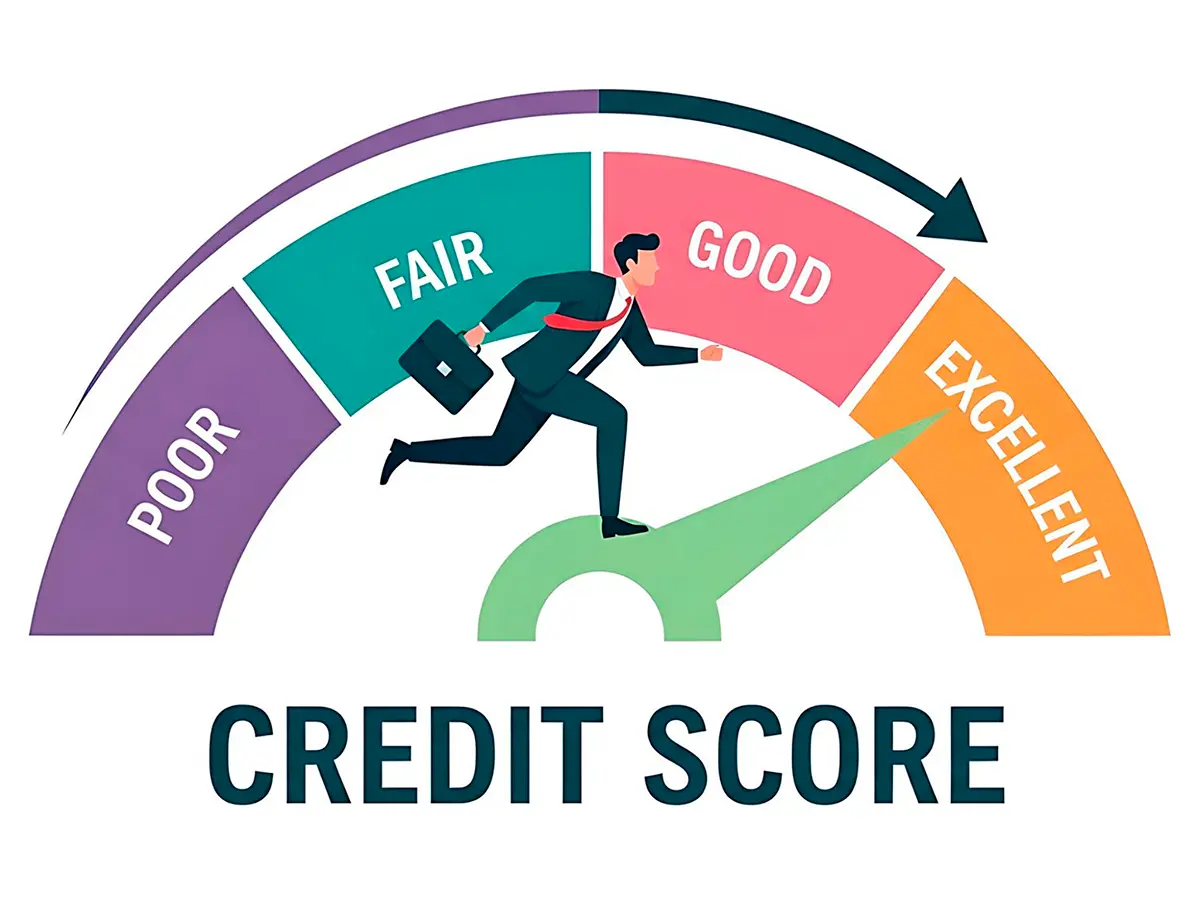
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
how to improve your credit score fast without panic
Start with the levers that move quickly
Your score can shift within a statement or two when you lower revolving balances. Focus on utilization: the percent of credit you use. Pay cards down below 30% of each limit; below 10% is even better. Make a mid-cycle payment so the statement cuts low. Ask for a credit limit increase that doesn't require a hard pull. Avoid new charges until the update posts. This is fast, convenient, and cheaper than interest.
- Send a small payment right after payday; repeat weekly. Micro-payments keep utilization low all month.
- Move due dates so they land after your paycheck, not before.
- Target the highest-APR card first to save cash while improving ratios.
- Keep one small balance reporting and pay it off the day it posts for easy rhythm.
Clean obvious errors
Pull your free credit reports from all three bureaus and scan for wrong balances, duplicate accounts, or misreported late payments. Dispute clearly inaccurate items online and upload statements, payoff letters, or identity-theft affidavits. Freeze your credit to block new fraud while you clean up. Pragmatic caveat: fixes usually post in 30 - 45 days, so "fast" often means the next cycle, not tomorrow.
Add positive data with minimal cost
- Become an authorized user on a long, low-utilization, no-late account (no need to use the card). This can boost history and limits quickly if the issuer reports.
- Report rent or utility payments through reputable services if the fee is low; steady on-time history helps thicken thin files.
- A small credit-builder loan at a credit union returns your savings at the end and adds payment history without big interest costs.
- A no-annual-fee secured card with a refundable deposit can establish positive activity; keep charges tiny and pay early.
Payment rhythm that sticks
Automate the minimum on every account, then add one planned extra payment mid-cycle. Set alerts for statement-close dates. Convenience matters because consistency builds points. On the bus ride home, I opened my card app, pushed a $60 mid-cycle payment, and set an autopay for the minimum - two weeks later, my score ticked up 18 points after the statement updated. Results vary, but the routine is simple and cheap.
What to avoid while optimizing
- Don't close old accounts; age matters.
- Don't open multiple new lines at once; new inquiries and young accounts can dip your score.
- Don't let a settlement report as "paid for less" if you can negotiate "paid in full."
- If you'll apply for a mortgage within 60 days, avoid new accounts and hard pulls.
Long-term habits that quietly compound
- Never pay late - payment history is king.
- Keep utilization under 10% when possible.
- Diversify slowly with low-fee products; prefer community banks or credit unions.
- Let accounts age; patience is free.
- Check reports quarterly and lock your credit by default.
- Keep a small emergency buffer so you don't carry balances after surprises.
Quick checklist for this month
- Download all three reports; note statement-close dates.
- Autopay the minimum; schedule a mid-cycle extra.
- Pay down balances to under 10% reporting.
- Request a soft-pull limit increase.
- Dispute one clear, documented error.
- Set utilization and payment alerts in your banking apps.
- Consider adding rent or a trusted authorized-user line.
- Freeze credit to stop unauthorized accounts.
Credit usually moves at the speed of statements. With a cost-conscious plan - lower balances, accurate reports, and steady, automated payments - you get quick wins now and a sturdier score for the long run. Fast is nice; durable is better.
Ways to improve your credit score - Paying your loans on time - Not getting too close to your credit limit - Having a long credit history - Making ...
Lowering your credit utilization ratio will often boost your credit scores, especially if your starting point is above the ideal 30% mark.
The best practice is to pay your credit card bills in full every month. If you can't, pay as much as possible. Try to keep your credit utilization rate below ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.